‘Move Your Money’ app (#OWS)
One of the most aggravating things about the credit crisis, and the (lack of) response to the credit crisis, is that the banks were found to be gambling with the money of normal people. They took outrageous risks, relying on the F.D.I.C. insurance of deposits. It is clearly not a good system and shouldn’t be allowed.
In fact, the Volcker Rule, part of the Dodd-Frank bill which is supposed to set in place new regulations and rules for the financial industry, is supposed to address this very issue, or risky trading on deposits. Unfortunately, it’s unlikely that the Volcker Rule itself goes far enough – or its implementation, which is another question altogether. I’ve posted about this recently, and I have serious concerns about whether the gambling will stop. I’m not holding my breath.
Instead of waiting around for the regulators to wade through the ridiculously complicated mess which is the financial system, there’s another approach that’s gaining traction, namely draining the resources of the big banks themselves by moving our money from big banks to credit unions.
I’ve got a few posts about credit unions from my guest poster FogOfWar. The basic selling points are as follows: credit unions are non-profit, they are owned by the depositors (and each person has an equal vote- it doesn’t depend on the size of your deposits), and their missions are to serve the communities in which they operate.
There are two pieces of bad news about credit unions. The first is that, because they don’t spend money on advertising and branches (which is a good thing- it means they aren’t slapping on fees to do so), they are sometimes less convenient in the sense of having a nearby ATM or doing online banking. However, this is somewhat alleviated by the fact that there are networks of credit union ATM’s (if you know where to look).
The second piece of bad news is that you can’t just walk into a credit union and sign up. You need to be eligible for that credit union, which is technically defined as being in its field of membership.
There are various ways to be eligible. The most common ones are:
- where you live (for example, the Lower East Side People’s Federal Credit Union allows people from the Lower East Side and Harlem into the field of membership)
- where you work
- where you worship or volunteer
- if you are a member of a union or various kinds of affiliated groups (like for example if you’re Polish)
This “field of membership” issue can be really confusing. The rules vary enormously by credit union, and since there are almost 100 credit unions in New York City alone, that’s a huge obstacle for someone to move their money. There’s no place where the rules are laid out efficiently right now (there are some websites where you can search for credit unions by your zipcode but they seem to just list nearby credit union regardless of whether you qualify for them; this doesn’t really solve the problem).
To address this, a few of us in the #OWS Alternative Banking group are getting together a team to form an app which will allow people to enter their information (address, workplace, etc.) and some filtering criteria (want an ATM within 5 blocks of home, for example) and get back:
- a list of credit unions for which the user is eligible and which fit the filtering criteria
- for each credit union, a map of its location as well as the associated ATM’s
- link to the website of the credit union
- information about the credit union: its history, its charter and mission, the products it offers, the fee structure, and its investing philosophy
It’s a really exciting project and we’ve got wonderful people working on it. Specifically, Elizabeth Friedrich, who has amazing knowledge about credit unions inside New York City (our plan is to start withing NYC but then scale up once we’ve got a good interface to add new credit unions), Robyn Caplan, who is a database expert and has worked on similar kinds of matching problems before, and Dahlia Bock, a developer from ThoughtWorks, a development consulting company which regularly sponsors social justice projects.
The end goal is to have an app, which is usable on any phone or any browser (this is an idea modeled after thebostonglobe.com’s new look- it automatically adjusts the view depending on the size of your browser’s window) and which someone can use while they watch the Daily Show with Jon Stewart. In fact I’m hoping that once the app is ready to go, we go on the Daily Show and get Jon Stewart to sign up for a credit union on the show just to show people how easy it is.
We’re looking to recruit more developers to this project, which will probably be built in Ruby on Rails. It’s not an easy task: for example, the eligibility by location logic, for which we will probably use google maps, isn’t as easy as zipcodes. We will need to implement some more complicated logic, perhaps with an interface which allows people to choose specific streets and addresses. We are planning to keep this open source.
If you’re a Rails developer interested in helping, please send me your information by commenting below (I get to review comments before letting them be viewed publicly, so if you want to help, tell me and won’t ever make it a publicly viewable comment, I’ll just write back to your directly). And please tell your socially conscious nerd friends!
What’s the Volcker Rule?
I wrote recently about the #OWS Alternative Banking working group preparing public comments on the Volcker Rule. I wanted to give a little bit more context. This is especially important right now because the watering-down period by financial lobbyists is getting intense.
The original Volcker Rule essentially states that banks shouldn’t do proprietary trading at all and they should also not invest in hedge funds or provate equity funds or in any way be liable for losses on such funds.
The idea is that the government and thus the taxpayer is backing (through the FDIC) the money inside banks and those banks shouldn’t use that insurance while at the same time risking the deposits themselves just to make a quick buck. To actually see this law, see Section 619 in the Dodd-Frank act. The law itself is only 11 pages, and some of that is around timing of implementation, so it’s a quick read.
Again, this 11-page document states what the Volcker Rule is supposed to implement. It summarizes the high-level thinking behind the rule. More importantly, the regulators’ mandate is to write a detailed rule that complies with what’s written in the law. When they ask for comments on the rule, they’re asking how well the rule implements the law.
This sounds pretty clean cut, but of course there are grey areas: for example, the law states that if banks fail to comply with the no-prop trading or hedge fund investing rules, then they’ll get punished by having higher capital requirements as well as fines. But it fails to say how stringent those punishments will be. So one way to technically implement the law is to make the punishment trivial.
The law also claims that the banks should be allowed to trade outside their clients’ direct interests in the name of hedging risks. The granularity of that allowed “hedging” is critical, since if they are hedging at the trade level, that’s very different from hedging at the macro level. The best example I’ve heard of this is that the bank may decide there’s “inflation risk” in their portfolio and start investing in long-term inflation hedges; then this really becomes more of a bet than a hedge but it depends on how you look at it and more importantly how one defines the word hedge.
To a large extent I feel like this could be resolved if we force a short-term horizon on the hedging basis. In other words, it’s a hedge if you can argue that you bought a bunch of 1-month puts so you need to hedge your risk on that one month period. However, a 5-year inflation outlook is clearly more of an opinion. On the other hand, forcing banks, as a group, to think in short horizons has its own dangers.
The law also states that banks are allowed to invest in certain U.S.-backed agencies:
PERMITTED ACTIVITIES… The purchase, sale, acquisition, or disposition of obligations of the United States or any agency thereof, obligations, participations, or other instruments of or issued by the Government National Mortgage Association, the Federal National Mortgage Association, the Federal Home Loan Mortgage Corporation, a Federal Home Loan Bank, the Federal Agricultural Mortgage Corporation, or a Farm Credit System institution chartered under and subject to the provisions of the Farm Credit Act of 1971 (12 U.S.C. 2001 et seq.), and obligations of any State or of any political subdivision thereof.
There are those who claim that we need to expand the above rule for the sake of national security and to prevent a deep, world-wide depression. Specifically, in this article in the Financial Times, the lobbyists are working hard to allow prop trading in European bonds, a huge market which is currently stipulated to be out of bounds:
They point out that Dodd-Frank exempts US sovereign bonds from the general prop trading ban for fear of disruptions. “What happens if you remove the US banks from Europe and they dump the stuff? Prices could collapse,” said Doug Landy, a regulatory lawyer at Allen & Overy.
There are lots of other permitted activities that don’t necessarily make sense to the historian of how other firms have gotten themselves into trouble: interest rate swaps (which are surely necessary tools for hedging basic bank hedging but it doesn’t seem to be restricted to hedging), spot commodities, foreign currency, and all kinds of loans (including repos). There are plenty of ways for banks to put deposits at risk within these instrument classes.
My conclusion is that, when the Alternative Banking group sends feedback to the regulators, we should separate comments on the implementation of the rule (e.g., what risk measures should be used and in how much detail they should be specified) from comments on the underlying law (e.g., whether this is actually preventing conflicts of interest).
The regulators are supposed to fix problems with the rule, but they can’t fix problems with the law (it takes an act of Congress to fix those). To the extent that we have problems with what’s in the law itself, it is worth a separate discussion about what the best way is to get those addressed.
Who takes risks?
One of my readers sent me a link to this blogpost by James Wimberley, which talks intelligently about safety nets and their secondary effects (it also has a nifty link to the history of bankruptcy laws in the U.S.).
I want to hone in on one aspect he describes, namely how, in spite of people in the U.S. considering themselves entrepreneurial, we are not so much. His theory is that it’s because of a lack of safety net: people are worried about losing their health insurance so they don’t leave the safety of their job. Here’s Wimberley’s chart of entry density, defined as the rate of registration of new limited liability companies per thousand adults of working age, by country:

The question of who takes risks is interesting to me, and made me think about my experiences in my various jobs. In fact this dovetails quite well with another subject I want to post on soon, namely who learns from mistakes; I have a theory that people who don’t take risks also don’t learn from mistakes well. But back to risktakers.
It kind of goes without saying that people in academics are not risk-taking entrepreneurs, but I’ll say it anyway – they aren’t. In fact it was one reason I wanted out- I’m much more turned on by risks than the people I met inside academics. In particular I don’t want to have the same job with the same conditions for the rest of my life, guaranteed. I want adventure and variation and the excitement of not knowing what’s next. When I went to a hedge fund I thought I would find my peeps.
However, most of the people I worked with at D.E. Shaw were really not risk takers at all, in spite of the finance cowboy image that they are so proud of. In fact, these were deeply risk averse people who wanted total control over their and their children’s destinies.
Moreover, the students I meet in finance programs (I took a few classes at Columbia’s when I knew I was leaving academic math) and who hope to someday work at JP Morgan are some of the most risk averse people ever. They are essentially trying to lock in a huge salary in return for working like slaves for a huge system.
Fine, so finance attracts people who are risk averse (and love money). That may be the consequence of its reputation and its age. So where are the risk takers? They must be some other field. How about startups?
What has surprised me working at a startup is that a majority of them are also not what I’d consider risk takers. There are a few though. These few tend to be young men with no families. Kind of the “Social Network” model of college aged boys working out of their dorm rooms. The women tend to be unmarried.
This is completely in line with Wimberley’s theory of safety nets, since it seems like once these men find a wife and have a kid they settle (speaking in general) into a risk averse mode. Once the women get married they tend to leave altogether.
In fact I’m kind of an oddball in that I’m married and have three kids and I actually love risk taking. Part of this is that I get to depend on my husband for health insurance, but that’s clearly not the only factor, since you’d expect lots of women whose husbands had steady jobs to be joining startups, but that’s not true.
I also have a feeling that the enormous amount of effort people tend to put into proving their credentials has something to do with all of this- when you take risks you are without title, you win or lose on your own luck and hard work. For a culture with a strong desire to be credentialed that’s a tough one.
I don’t really have a conclusion today but I’m thinking that the story is slightly more complicated than just safety nets. I feel like maybe it starts out as a safety net issue but then it becomes a cultural assumption.
What does “too big to fail” mean?
The Alternative Banking meeting yesterday was really good, and interesting. During the discussion someone raised the point that when we describe a bank as “too big to fail,” we almost always measure that in terms of their assets under management, or the percent of deposits they have, or their net or gross exposures. In other words, we measure the size of the individual institution.
However, what’s just as important in terms of being “too big” is the extent to which a given bank is too interconnected, meaning they are in deals with so many other counterparties that if they go under, they would set off a cascade of contractual defaults which would cause chaos in the entire system. In fact Lehman was like this, too interconnected to fail. It’s funny but I’m pretty sure Lehman wasn’t too big to fail under many of the current definitions.
Although this question of counterparty risk is brought up consistently, it’s never adequately addressed in terms of risk; we are still more or less asking people to measure the volatility of their PnL, and we typically don’t force them to expose their counterparty exposure in stress tests and whatnot.
What if we addressed this directly? How could we regulate the interconnectedness of a given institution? What would be the metric in the first place and what limits could we set? How could we set up a regulator to convincingly check that institutions are sticking to their interconnectedness quotas?
I’ll keep thinking about this, they are not easy questions. But I think they are important ones, because they get to the heart of the current problems more than most.
A further question brought up yesterday was, how do we know when the entire financial system is too big? I guess we don’t need any fancy metrics to say that for now we just know.
Alternative Banking meeting today
We’re meeting from 3-5pm today at 1401 International Affairs Building on Columbia Campus. That’s at Amsterdam and 118th, on the 14th floor. The meeting is open to everyone.
It’s going to be an interesting meeting today. Lots has happened this week with the movement, obviously, and it’s super important to keep the conversation going and productive. We got some press coverage in the Financial Times and perhaps because of that I’ve added quite a few new names to the email list. I’m very much looking forward to meeting the new members of our group.
Bloomberg’s decision with removing the tents from the park and the 2-month anniversary protests got lots of attention, not all of it positive. I participated in the protest the other day with my son, and since then I’ve had a few thoughts about it.
This movement is a big deal and can potentially be a bigger deal. It’s certainly one of the things I care about deeply. I understand people’s frustration and defiance, because even just thinking outside the system when it’s this huge and embedded is an act of defiance. But what I don’t want to see is the movement losing its head and giving in to anger and rage. Especially because it inevitably becomes something extremely narrow- us against the police, or us against Bloomberg.
The truth is the police, at least the ones on the ground in riot gear, have very little to do with setting up this system. Bloomberg has more to do with it, but he’s still just another scavenger picking out the juiciest meat of the system. What we need to do is understand the bigger picture and try to improve things in a meaningful and positive way.
That’s not to say that I want to work within the system to change it. I’m not that naive to think that people give up their honeypots so easily: this will be a war against corruption and vested interests. But I’d rather spend my time rooting out real corruption (like Jack Abramoff has done in this amazing Bloomberg article) and proposing realistic alternatives than being vaguely angry at the wrong things.
The democratic system that the OWS movement has created is based on the idea of mutual respect and trust. We need to enlarge that sense of trust to more and more people, including the cops and including the mayors. We want to invite them to join us, or at least to respect us.
It’s my experience that most people want to live in a just world- even if they take advantage of injustices for themselves. The majority of people working in the financial system see it as unfair and unreasonable. One reason they let things slide is that they really don’t believe the system could be changed; they don’t have the imagination or the faith to believe that. So that’s actually what we can and should provide: imagination and faith.
No system is perfect, of course, but there are certainly systems that are less imperfect, and we should be envisioning them and a path towards them which is reasonable and not terrifying. If we could do that we would get support rather than pepperspray. I know I’m sounding idealistic, but that’s actually what we need right now. After all the original protest started with nothing more than silly hand signals and ideals; its international growth has proven that ideals resonate with people.
Occupy the SEC: commenting on the Volcker Rule
One of the subgroups of the Alternative Banking group is an #OWS group called Occupy the SEC. Their goal is to make comments on the Volcker Rule before the public commenting period ends on January 13th, 2012.
At our last meeting we distributed a sheet where people put their email addresses and listed fields of expertise so that the people in Occupy the SEC could ask us specific clarifying questions about what the current version of the Volcker Rule says.
If you think you could have time to help them, please email them at occupythesec@gmail.com and tell them what your fields of expertise are. They are mostly looking for financial expertise and people who speak legalese, but anyone who is a good and careful reader will be super useful too.
My experience at Riskmetrics working with Value-at-Risk (VaR), where I was actually working on methodology questions of VaR usage for credit instruments like CDS, makes me pretty useful to these guys.
This morning I’ve been reading about the proposed risk reporting requirements for the “covered bank entity”. Basically they are required to report daily 99th percentile VaR. But left out are all other details, including:
- whether they should use parametric, historical, or MonteCarlo VaR methods,
- what their lookback period is (if historical)
- what their decay length is (if MonteCarlo)
- what exactly they need to admit as risk factors
- why they would ever use parametric VaR outside of stocks, since parametric VaR sucks outside of stocks.
They are also asked to report the skew and kurtosis of their daily PnL, but I believe are only required to report this for daily numbers on a quarterly basis, which means there’s no chance in hell those will be meaningful numbers.
How about this instead: report all three kinds of VaR, with a year lookback for historical VaR, and with various decay lengths for MonteCarlo VaR. Specify the risk factors and ask for each risk factor’s sensitivity (which is like a partial derivative if we are using parametric VaR) as well as min and max returns (if we are using historical VaR). Report skew and kurtosis using daily numbers with 2 years of data.
Even better if they abandon this altogether and go for something benchmarked as I discussed in this post.
There seems to be no stipulated need to report counter-party exposure or risk, at least in this section (Appendix A). This seems particularly egregious considering the current situation, namely that we are waiting for European sovereign debt defaults to cause broken CDS hedges through collapsing counterparties. We know this would happen, but we somehow don’t want to know more details.
This is only a few pages of the Volcker Rule, though, out of I think something like 550. We need your help for sure!
Protest today
I don’t know where you’re going today after work but there’s going to be a massive protest in front of city hall starting at 5pm.
See outrageous footage of this morning on Wall Street here coming from the Wall St. Journal.
I’m thinking of going with my oldest son, who is very excited about it and desperately wants to join, especially if it means missing school (but I think his enthusiasm would be sustained if he got to go to bed late as well). I actually brought him with me that very first day I went down to check out the protest on day 13, and he’s been bragging about being in the “opening bell march” ever since.
He also thinks kids should be able to vote (and wants to join the Alternative Banking working group). Here’s an article suggesting we should do something even more extreme, namely let people vote from birth. It’s an interesting idea and could encourage families to engage in politics more.
The truth is my son thinks and cares about issues of politics and justice more than most grownups. In fact he once was a huge Obama supporter, and around the election he’d watch Obama’s speeches after finishing his homework. I thought he must just be missing most of it, since it was mostly rhetoric, and after all he was only 8 years old at the time, but then something happened which changed my mind.
We were leaving a restaurant after eating dinner, and he held the door open for me to push the stroller through with his baby brother (I think this was actually the first time we ever went out to eat with the baby). As the door closed I saw little girl, maybe 3, who looked dangerously close to getting her hand caught in the door, and I jumped back to hold the door open. My son told me he felt bad that he almost let the door hurt the little girl, to which I replied, “first of all she wasn’t really that close to the door, and second of all it’s not your responsibility to worry about other people’s kids.” My son replied, “but when Obama says that we rise and fall as a people, he means that’s exactly what our responsibilities are!”
I heard rumors that people in Zuccotti Park, who I think are still being let in single-file through a big gate with cops doing a kind of airport check-in, have been told that they aren’t allowed to “carry signs inside the park.” First of all that’s ridiculous and second of all that’s not going to make the Bloomberg administration look reasonable. Is Bloomberg going for a legacy of squelching a non-violent legal protest? I thought he was all about bringing engineering to New York.
Here’s the poster for today’s protests. I’m a bit confused by the juxtaposition of the word “non-violent” and the presence of tanks, maybe someone could explain that one to me this is a reference to Tiananmen Square I’ve been told:

In memory of Sally Hale
When I was five years old my parents moved to Lexington, Massachusetts. My first friend, so my oldest friend, was my next door neighbor Sally Hale, the mom of the twin boys next door Ezra and Caleb, two years older than me and the same age as my brother. Sally, who also had two older boys, so four altogether, took me under her wing as the daughter she never had. I understand that so well now that I have three sons and the boy downstairs from us has a sister. I want to adopt her, I want her to always feel welcome in my home and part of the Sunday morning pancakes ritual (she is).
I grew up in Lexington, not moving away until college, and Sally and her family were an essential part of my life. Looking back at it now it was pretty amazing; Sally and Ken were lefties, had parties with Noam Chomsky and other activists (Ken was a linguist at M.I.T.), they were super involved with all sorts of underrepresented groups through Ken’s field work with various undocumented and mostly dying languages. I have a story about Ken, which may be a myth but gives you an idea of the values I was exposed to.
Ken was called as an expert witness in Australia on the question of whether some indigenous people had the rights to land. The court wanted documented evidence that they had been there for so many thousands of years to grant the rights, but they didn’t have any written records. Ken, being an expert on evolution of languages, argued that due to the aspects of their language compared to the languages in the area, he could confirm their location there for much longer. They got the land.
As a child, of course, I didn’t know anything about politics or even much about human rights, so my experience with them was through their everyday life. I was always invited in to Sally’s house (it was the family’s house but it was really Sally’s house), and the warmth and kindness they bestowed on each other and me made me visit often, if not every day during certain times, especially when my brother and Caleb and Ezra regularly played D&D.
Sally introduced me to music, a gift I will always thank her for, a private world of unrestrained beauty, which was particularly precious to me because outside of this world I was a chubby, nerdy misfit. She taught me to play the penny whistle when I was 5 or 6, and encouraged me to start the piano when I was 7. She taught me to sing rounds (“hey ho nobody home”) and seemed to never get tired of singing them with me. Sometimes she’d take out her guitar and sing old 60’s folk songs about peace and love and teach me to harmonize. When I started playing the violin, I would play fiddle tunes in the evenings on the porch with Ken. We even entered fiddle contests together a few times (we never won anything but we were proud to be part of it).
Sally knitted me mittens to keep my hands warm as I went sledding in her backyard with Caleb and Ezra and my brother. She knitted during movies we would all go to together downtown. For me, listening to the click click clicks coming from her knitting needles in the complete darkness of the movie was a kind of miracle. She later taught me to knit, and we spent many hours in my adulthood talking about knitting and sharing yarn and tips.
Sally was an expert seamstress and taught me to sew, and sewed me clothes when I was little and even helped me sew a dress for myself in graduate school. She loved going to house auctions and would buy beautiful little objects which came from some old lady’s sewing kits. Later when I started sewing and knitting for my kids she gave me some of her auction buttons, collections of perfect little white pearls strung together on ancient string. I still have some.
Sally baked; she’d call us in from outside to give us kids thick slabs of bread, still warm from the oven, with butter and cinnamon sugar for a snack. We’d be sitting on the kitchen stools, eager to get back to sledding, or flashlight tag, or hanging out on the tree fort, eating our delicious bread with some hot cocoa and having no idea of how lucky we all were.
I remember when Sally decided to get a degree in nursing. In fact I thought she was already qualified for absolutely anything, considering how ridiculously competent she was at everything involving nurturing and healing, but she explained to me how much she needed to study. I remember helping her quiz herself on anatomy, with a huge book with mysterious pictures of the human body.
Sally showed me the delights of creation and creativity and of nurturing them both. When I think about how to have kids, how to have a happy family, I think about her method of making sure the basic materials are there, fostering a supporting environment, fostering the desire and the know-how, and then letting go. She did all that for me, and I’m so grateful.
I am very lucky I was able to see Sally recently. I visited her after math camp ended, and I brought my two older sons with me to see her. I also got to see Ezra with his happy family. It was nice to be able to surround her with abundance, evidence of her legacy of warmth and creation. She passed away recently and I am honored to speak at her memorial service this coming weekend. I’m honored to have been so loved by her.
Zuccotti Park just now: updated
Police are keeping people out of the park.


In addition, the Atrium at 60 Wall is closed all day. They haven’t said when it will reopen.
You can register your opinion on this handy New York Times graphic.
They’re back in! Check it out live.
Hey Google, do less evil.
I recently read this article in the New York Times about a business owner’s experiences using Google Adwords.
For those of you not familiar with the advertising business, here’s a geeky explanation. As a business owner, you choose certain key words or phrases, and if and when someone searches on Google with that word or phrase, you bid a certain amount to have your business shown at the top of the return searches or along the right margin of the page. You fix the bid (say 4 cents) beforehand, and you only pay that 4 cents when someone actually clicks. The way your position in the resulting page is determined is through an auction.
Say, for example, you and your competitors have all bid different amounts for the keyword “monodromy”. Then every time someone searches for “monodromy”, all the bids are sorted after being weighted by a quality score, which is a secret sauce created by Google but can be thought of as the probability that some random person will click on your ad.
This weighting makes sense, since Google is essentially determining the expected value of showing your ad: the product of the amount of money they will get paid if someone clicks on it (again, because they only get paid when the click occurs) and the probability of that event actually happening. Quality scores are actually slightly more than this, and we will get back to this issue below.
Moreover, once the sorting by expected value is done, your actual payment is determined not precisely by your bid but by the minimum bid you’d need to still maintain your position in the auction. This is a clever idea that gets people to raise their bids in order to win first place in the auction but not need to pay too much… unless there’s another guy who is determined to win first place.
Of course, it’s not always necessary to pay Google to get clicks. Sometimes your business will show up in the “organic searches” anyway- say if the name of your company is well-chosen for your product. So if you’re selling oak tables and the name of your company is “Oak Tables” then you may not need to pay anything for the that key phrase (but you may be willing to pay for the phrase “tables oak cherry”).
Back to the business owner. He decided to experiment with turning off Adwords, in other words he decided to rely on the results of organic searching instead of paying for each click. It didn’t end well- he gave up after a week because business was bad. The thing that caught my eye in this article was the suggestion that, when he turned off the payment, Google also became stingy with showing his free results. In other words, Google seems to be juicing their results (which is likely done through the quality score function) to punish people for not being in the pay-for-clicks program:
What is surprising to me is the steep drop in organic visits, the clicks from free links. They have fallen 47 percent, from 328 to 173. Stopping the AdWords payments seems to have affected unpaid traffic as well. According to everything I’ve been told about search engine optimization, this shouldn’t have happened. But from a business standpoint, it makes sense to me. Google is in business to make money by selling searches. Why shouldn’t it boost the free listings of its paying customers — and degrade the results when they stop paying? It’s also possible that people are more inclined to click on free results when they see the same company has the top paid link. Maybe it’s conscious, maybe it’s not. I’d be interested to hear any theories readers may have as to why my organic traffic took such a fall.
One theory I have is that it’s unfortunately impossible to figure out, because Google doesn’t seem to think they need to explain anything to anyone, even though they have become the arbiter of information. It’s a scary prospect, that they have so much control over the way we see and understand the world, and between you and me their “do no evil” motto isn’t sufficiently reassuring to make me want to trust them on this completely.
A friend of mine recently had a terrible experience with Google which makes this lack of clarity especially frustrating. Namely, some nut job decided to post evil stuff about him and someone else through comments on other peoples’ blogs. There was no way for him to address this except by asking the individuals whose websites had been used to take down the posts. In particular, there was no way for my friend to address the resulting prominent Google search results through the people working at Google- they don’t answer the phone. It doesn’t matter to them that people’s lives could be ruined with false information; they decided many years ago that they are not in the client service industry and haven’t looked back. Their policy seems to be that, as long as there is no actual and real threat of violence, they have no obligation to do anything.
That would be okay for a small startup with little influence on the world, but that’s really not what Google is. Google wields tremendous powers, and their quality score algorithm is defining our world. At this point they have a moral responsibility to make sure their search result algorithms aren’t ruining people’s lives.
What if it were possible to mark a search results as “inappropriate”? And then, given enough votes, the quality score would be affected and the listing would go down to the bottom of page 19. I realize of course that this could be used for good as well as for bad – people could abuse such a system as well, by squelching information they don’t want to see. But the problem with that argument is that it’s already happening, just inside Google, where we have no view. So in other words yes, it’s a judgment call, but I’d rather have a person (or people) do that than an algorithm.
Morning poem
Every morning
the world
is created.
Under the orange
sticks of the sun
the heaped
ashes of the night
turn into leaves again
and fasten themselves to the high branches —
and the ponds appear
like black cloth
on which are painted islands
of summer lilies.
If it is your nature
to be happy
you will swim away along the soft trails
for hours, your imagination
alighting everywhere.
And if your spirit
carries within it
the thorn
that is heavier than lead —
if it’s all you can do
to keep on trudging —
there is still
somewhere deep within you
a beast shouting that the earth
is exactly what it wanted —
each pond with its blazing lilies
is a prayer heard and answered
lavishly,
every morning,
whether or not
you have ever dared to be happy,
whether or not
you have ever dared to pray.
from Dream Work (1986) by Mary Oliver
Postage paid protest
I’m glad I got a new laptop with sound, because now I can listen to and watch this awesome YouTube video with suggestions to keep Wall Street occupied.
The sin of debt
It’s fascinated me for a while how people use language to indicated the relationship between money and morality. David Graeber’s book about debt took this issue on directly, but even before reading it I had noticed the disconnect between individual debt and corporate debt.
It was clear from my experience in finance that debt is something that, at the corporate level, is considered important – you are foolish not to be in debt, because it means you’re not taking advantage of the growth opportunities that the business climate affords you. In fact you should maximize your debt within “reasonable” estimates of its risk. Notable this is called leveraging your equity, a term which if anything sounds like a power move.
That just describes the taking on of debt, which for an individual is something they are likely not going to describe with such bravado, since they’d be forced to use measly terms such as “I got a loan”. What about when you’re in trouble with too much debt?
My favorite term is debt restructuring, used exclusively at the corporate (or governmental) level. It makes defaulting on ones debt a business decision by a struggling airline or what have you, and the underlying tone is sympathy, because don’t we want our airlines (or other american companies) to succeed?
When you compare this language and its implied morality (neutral) to the moralistic preaching of late-night talk radio, it’s quite stark. It’s made clear on such shows that debt is a sin, that the reason the show is a success is that it’s entertainment to hear how messed up the callers’ finances are, and to hear the radio host drill into their most private details in the name of ferreting out that sin.
The Suzy Ormon show is another example of this, and this blog entry is a great description of the emotional and spiritual repentance required in our culture when one is in debt, bizarrely combined with her urging you to go out and consume some more.
For the individual there is no debt restructuring available – at best you can get your debt consolidated, but the people who do that are themselves considered icky. There’s no clean way to deal with out-of-control debt as an individual.
Until now! I found an interesting article the other day which somehow excludes certain people from the moral failing of being in debt – namely, if they have the help of another powerful buzzword – a moral reclamation if you will – namely, “entrepreneur.” Because we all want our entrepreneurs to succeed!
The fact that the program doesn’t apply to most of a typical person’s student debt load is only partly relevant – for me, the fascinating part is the way that, when you stick in the word “entrepreneur,” you suddenly have the vision of someone who shouldn’t be saddled with debt, who is immediately forgiven for their sins. It brings up the question, can we perform this moral cleansing for other groups of people who are currently in debt?
What if we coopted the language of the corporations for the individual? I’d love to hear people talking about large-scale restructuring of their debt. Just the phrase makes me realize its possibilities. One of the main tools of leverage for such talks is the amount of money on the table. If sufficiently many people got together to formally restructure their credit card debts, what would the banks do? What could they do except negotiate?
Here’s a graphic I like just in case you haven’t seen it yet:
Overfitting
I’ve been enjoying watching Andrew Ng’s video lectures on machine learning. It requires a login to see the videos, but it’s well worth the nuisance. I’ve caught up to the current lecture (although I haven’t done the homework) and it’s been really interesting to learn about the techniques Professor Ng describes to avoid overfitting models.
In particular, he talks about iterative concepts of overfitting and how to avoid them. I will first describe the methods he uses, then I’ll try to make the case that they are insufficient, especially in the case of a weak signal. By “weak signal” I mean anything you’d come across in finance that would actually make money (technically you could define it to mean that the error has the same variance as the response); almost by definition those signals are not very strong (but maybe were in the 1980’s) or they would represent a ridiculous profit opportunity. This post can be seen as a refinement of my earlier post, “Machine Learners are spoiled for data“, which I now realize should have ended “spoiled for signal”.
First I want to define “overfitting”, because I probably mean something different than most people do when they use that term. For me, this means two things. First, that you have a model that is too complex, usually with too many parameters or the wrong kind of parameters, that has been overly trained to your data but won’t have good forecasting ability with new data. This is the standard concept of overfitting- you are modeling noise instead of signal but you don’t know it. The second concept, which is in my opinion even more dangerous, is partly a psychological one, namely that you trust your model too much. It’s not only psychological though, because it also has a quantitative result, namely that the model sucks at forecasting on new data.
How do you avoid overfitting? First, Professor Ng makes the crucial observation that you can’t possibly think that the model you are training will forecast as well on new data as on the data you have trained on. Thus you need to separate “training data” from “testing data”. So far so good.
Next, Professor Ng makes the remark that, if you then train a bunch of different models on the training data, which depend on the number of variables you use for example, then if you measure each model by looking at its performance on the testing data to decide on that parameter, you can no longer expect the resulting model (with that optimized number of parameters) to actually do so extremely well on actually new data, since you’ve now trained your model to the testing data. For that reason he ends up splitting the data into three parts, namely the training data (60%), a so-called validation data set (20%) and finally the true testing set (the last 20%).
I dig it as an idea, this idea of splitting the data into three parts, although it requires you have enough data to think that testing a model on 20% of your data will give you meaningful performance results, which is already impossible when you work in finance, where you have both weak signal and too little data.
But the real problem is that, after you’ve split your data into three parts, you can’t really feel like the third part, the “true test data”, is anything like clean data. Once you’ve started using your validation set to train your data, you may feel like you’ve donated enough to the church, so to speak, and can go out on a sin bender.
Why? Because now the methods that Professor Ng suggests, for example to see how your model is doing in terms of testing for high bias or high variance (I’ll discuss this more below), looks at how the model performs on the test set. This is just one example of a larger phenomenon: training to the test set. If you’ve looked at the results on the test set at all before fixing your model, then the test set is just another part of your training set.
It’s human nature to do it, and that’s why the test set should be taken to a storage closet and locked up, by someone else, until you’ve finished your modeling. Once you have declared yourself done, and you promise you will no longer tweak the results, you should then find the person, their key, and test your model on the test set. If it doesn’t work you give up and try something else. For real.
In terms of weak signals, this is all the more important because it’s so freaking easy to convince yourself there’s signal when there isn’t, especially if there’s cash money involved. It’s super important to have the “test data set”, otherwise known as the out-of-sample data, be kept completely clean and unviolated. In fact there should even be a stipulated statute of limitations on how often you get to go out of sample on that data for any model at all. In other words, you can’t start a new model on the same data once a month until you find something that works, because then you’re essentially training your space of models to that out-of-sample data – you are learning in your head the data and how it behaves. You can’t help it.
One method that Ng suggests is to draw so-called “learning curves” which plot the loss function of the model on the test set and the validation set as a function of the number of data points under consideration. One huge problem with this for weak signals is that the noise would absolutely overwhelm such a loss estimate, and we’d end up looking at two extremely misleading plots, or information-free plots, the only result of which would be that we’ve seen way too much of the test set for comfort.
It seems to me that the method Ng suggests is the direct result of wanting to make the craft of modeling into an algorithm. While I’m not someone who wants to keep things guild-like and closed, I just don’t think that everything is as easy as an algorithm. Sometimes you just need to get used to not knowing something. You can’t test the fuck out of your model til you optimize on every single thing in site, because you will be overfitting your model, and you will have an unrealistic level of confidence in the result. As we know from experience, this could be very bad, or it could just be a huge waste of everyone’s time.
#Occupy Wall Street meeting and news
First, I wanted to mention that there will be an Alternative Banking meeting on Sunday from 3-5pm at 1401 IAB (14th floor of the International Affairs Building), Columbia University. This is on the corner of Amsterdam and 118th. Please come!
Next I wanted to mention that I’ve been hearing from other occupied cities, namely Occupy Oakland and Occupy LA. I’ve been meeting the most amazing people this way and I’m super grateful for that. I should be talking to Cheryl from Occupy LA later today, and it sound like her posse of occupiers have really been making things happen with something called the “Responsible Banking Measure” recently passed by the LA City Council. Awesome stuff, and I’ll post more as I learn it. My favorite part was the last line of her email, “let’s do this!”
Another inspiring figure is coming from Occupy Oakland, a photographer named Miles Boisen, whose trademark phrase, “struggle and snuggle,” is very close to my heart. He recently met a group of four protesters who were so fascinating that he asked them to tell a bit more about their story. First, here’s their picture:
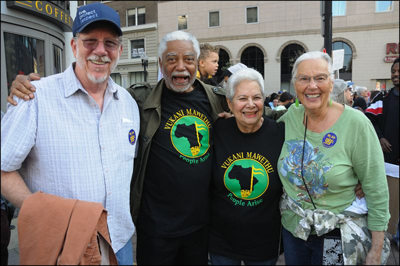
Next, here’s one of their stories:
Dear Myles,
It was wonderful to meet you at the time and place we did. I am happy to give you some background information. Feel free to use it (or not) any way you like.
I was born in San Francisco in 1944, the year that millions of Jews were being slaughtered by Hitlers minions in Europe. My mother, Hodee Edwards, is Jewish. My father, Harvey Richards, is of Welsh ancestry. I witnessed the 1950s in the streets of Oakland, watching my mother crying over the Rosenbergs execution, and experiencing the racism of our world through the eyes of my African American step father (George Edwards) and my sister (Lou Edwards). I dodged the FBI coming to my house to harrass my family and witnessed doors being slammed in the FBI’s faces as they sought to intimidate dissidents in Oakland. I traveled to the USSR in the summer of 1961, the year I graduated from high school, to help my father and his wife, my stepmother Alice Richards, make two films on ordinary life in the USSR. See this for a clip from that movie.
I entered UC Berkeley in the fall of 1961 and immediately joined the civil rights movement. My first demonstrations were against compulsory ROTC at Berkeley, a struggle that resulted in the cancellation of compulsory ROTC in my sophmore year. I participated in the sit-ins at Mel’s drive-in restaurants (see this for a clip of my father’s film showing those demos and a shot of me on the picket line), at the Sheraton Palace Hotel (see this which includes a shot of me being dragged out of the lobby by the SFPD) and along auto row on Van Ness in San Francisco in 1963 and 1964 against racial discrimination in hiring, then rampant all around the bay area. I spent 2 months in the San Francisco County Jail in San Bruno in 1966 for my efforts.
I resisted the draft from my graduation in 1966 when I was classified 1A to 1969 when the draft board just gave up on me and never sent me another nasty letter. See this for a slide show of events that took place on the day I was drafted (but slipped out of their grasp), Oct 18,1967 during the Stop the Draft Week events on the very same street Occupy Oakland’s general strikers walked down last Tuesday.
As you can see the events of those years are still very alive for me through the work I have done archiving my father’s film collection (see this). I have kept the memories of those movements alive because I believe in them now as I did then. So, for me, the Occupy Oakland movement is a dream come true. It finally gives voice to the cry for justice and sanity that has been silenced for so long under the hegemony of the Republican and Democratic Parties ever since the election of the crook, Richard Nixon, and continuing until the present day with the election of the most recent fraud, Obama the bomber.
I rejoice at the outpouring of outrage from our youth. They have made it possible for me to switch from the tiny minority who over the past 40 years have dissented against the American empire, to the 99% who are dissenting today. What a relief. I don’t know where this movement is headed nor how long it will last. But I do know that it has my whole hearted support and that it opens the door to ten thousand possibilities. I am in awe that I lived to witness it. Since I am retired now, my future plans are to continue to manage Estuary Press and the Harvey Richards Media Archive and to make sure that we do not forget our history, even as we are making it right now.
I guess you can’t call this brief, but I tried my best.
Thanks for asking, and hoping you don’t regret it,
Paul Richards
In praise of nerd kids
I’m a bit of an unusual mother. I don’t worry that my kids don’t have a bunch of friends, that they aren’t popular. I’d actually be more worried, to tell you the truth, if they were super popular. Actually one of my kids is verging on popular, and it’s kind of an issue.
See, the thing is, I love nerd kids. I love the way they are dreamy, and spaced out, figuring out a logical internal system that could never exist except in their minds, laughing to themselves about a joke they just made up, and rewriting songs with silly lyrics a la Weird Al Yankovic, whom they’ve never heard of.
Why? Because almost all of my favorite people in the world were total nerds, or at least outsiders, when they were kids, and I don’t think that’s a coincidence. There’s something about not fitting in, about maintaining an observer’s status, that keeps you from ever being subsumed by the vicious groupthink of seventh grade (and if you can resist that kind of peer pressure, you can resist anything).
By the way, I was a huge nerd in seventh grade, and I had exactly one friend. In fact I didn’t have any friends for a couple of months, and it was miserable. So I’m not saying that I’m hoping for an easy path for my kids. In fact I’m hoping for something kind of tough for my kids, which is probably why most other parents try hard to make sure their kids have playdates with lots of other kids and have spectacular birthday parties etc.
And it’s not that I don’t want my kids to have friends- I do, and they do, just not very many. As far as I’m concerned, two or three co-nerd friends is just about perfect. If we’ve got enough for a Dungeons and Dragons game, we’re good. I’m not ever going to make my kids feel bad for the fact that they’ve only ever played with each other, the kid who lives downstairs, and the kid who lives next door, because those kids are seriously nerdy and awesome.
One thing I hate though is the concept of the child prodigy. Unlike nerds, who live in a dream world of their own making, which I think is awesome, the child prodigy lives in a dream world of their parents’ making, which is weird and not good. I’ve known some of these kids, and they get totally addicted to a certain kind of adult attention, which of course doesn’t last past childhood. They never learn to rely on themselves for feeling accomplished.
I just don’t get it either- so what that a 10 year old can do calculus? What’s the big deal, are there calculus problems that the world needs solving that only this kid can do? No. Leave the kid alone to be a nerd for a few more years, then decide what he or she wants to do. The obsession in our culture with prodigy is just weird, it’s in the same boat with beauty pageants for 3-year-olds. So weird, bordering on creepy.
There are basically two kinds of nerds, from my experience. The first kind is the nerd who vaguely understands that there are social rules that he or she doesn’t understand but that everyone else does. This nerd thinks about that every now and then with something like surprise or maybe even alarm, but then goes back to thinking about more interesting things. My mom is a nerd like this: grew up in L.A. with the children of starlets and couldn’t wait to get to MIT. Built her own telescope in the backyard. That kind of thing.
Then there’s the second kind of nerd, which I was, the excruciatingly sensitive nerd who is fully aware of how much of an outsider he or she is – always aware of the cruelty of those in power, and always feeling for the various victims (who are usually someone else). This nerd is lucky if they survive adolescence without committing suicide, but pretty much from then on it’s good stuff (although never easy). Their favorite movie is Harold and Maude (or was in the 1980’s) and they tend to listen to music really loud whenever they can. Love those nerds.
Gaming the system
It’s not easy being a European bank right now. Everyone is telling them to boost capital, otherwise known as raise money, exactly at the time that much of their investments are losing value on the market because of the European debt crisis.
If I were the person running such a bank, I’d be looking at fewer and fewer options. Among them:
- Ask China for some of their money
- Ask investors for some of their money
- Ask a middle eastern country for some of their money
- Cut bonuses or dividends
- Change the way I measure my money
Of the above possibilities, 5) is kind of attractive in a weird way.
And guess what? That’s exactly the option that the banks are choosing. According to this article from Bloomberg, the banks have suddenly noticed they have way more assets than they previously realized:
Spanish banks aren’t alone in using the practice. Unione di Banche Italiane SCPA (UBI), Italy’s fourth-biggest bank, said it will change its risk-weighting model instead of turning to investors for the 1.5 billion euros regulators say it needs. Commerzbank AG (CBK), Germany’s second-biggest lender, said it will do the same. Lloyds Banking Group Plc (LLOY), Britain’s biggest mortgage lender, and HSBC Holdings Plc (HSBA), Europe’s largest bank, both said they cut risk-weighted assets by changing the model.
“It’s probably not the highest-quality way to move to the 9 percent ratio,” said Neil Smith, a bank analyst at West LB in Dusseldorf, Germany. “Maybe a more convincing way would be to use the same models and reduce the risk of your assets.”
Ya THINK?!
European firms, governed by Basel II rules, use their own models to decide how much capital to hold based on an assessment of how likely assets are to default and the riskiness of counterparties. The riskier the asset, the heavier weighting it is assigned and the more capital a bank is required to allocate. The weighting affects the profitability of trading and investing in those assets for the bank.
One reason I couldn’t stomach any more time at the risk company I worked at is things like this. We would spend week after week setting up risk models for our clients, accepting whatever they wanted to do, because they were the client and we were working for them. Our application was flexible enough to allow them to try out lots of different things, too, so they could game the system pretty efficiently. Moreover, this idea of the “riskiness of counterparties” is misleading- I don’t think there is an actual model out there that is in use and is useful to broadly understand and incorporate counterparty risk (setting aside the question for now of gaming such a model).
For example, the amount of risk taken on by CDS contracts in a portfolio was essentially assumed to be zero, since, as long as they hadn’t written such contracts, they were only on the hook for the quarterly payments. However, as we know from the AIG experience, the real risk for such contracts is that they won’t pay out because the writers will have gone bankrupt. This is never taken into account as far as I know- the CDS contracts are allowed for hedging and never impose risk on the overall portfolio otherwise. If the entity in question is the writer of the CDS, the risk is also viciously underestimated, but for a slightly more subtle reason, which is that defaults are generally hard to predict.
Here’s not such a crappy idea coming from Vikram Pandit (it’s in fact a pretty good idea but doesn’t go far enough). Namely, standardize the risk models among banks by forcing them to assess risk on some benchmark portfolio that nobody owns, that’s an ideal portfolio, but that thereby exposes the banks’ risk models:
Pandit is championing an idea to make it easier to compare the way banks assess risk. To accomplish this, he wants to start with a standard, hypothetical portfolio of assets agreed by regulators the world over. Each financial institution would run this benchmark collection through its risk models and spit out four numbers: loan loss reserve requirements, value-at-risk, stress test results and the tally of risk-weighted assets. The findings would be made public.
Then, Pandit wants the same financial firms to run the same measures against their own balance sheets – and to publish those results, too. That way, not only can investors and regulators compare similar risk outputs across institutions for their actual portfolios, but the numbers for the benchmark portfolio would allow them to see how aggressively different firms test for risks.
I think we should do this, because it separates two issues which banks love to conflate: the issue of exposing their risk methodology (which they claim they are okay with) and the idea of exposing their portfolios (which they avoid because they don’t want people to read into their brilliant trading strategies). I don’t see this happening, although it should- in fact we should be able to see this on a series of “hypothetical” portfolios, and the updates should be daily.
As a consumer learning about yet more bank shenanigans, I am inspired to listen to George Washington:
Truth Values
Just two quick things today.
First, I’m going to see Truth Values: One girl’s romp through M.I.T.’s male math maze this Saturday, with a couple of buddies of mine. It’s been recommended to me by a bunch of my math friends, and tickets are available here. It’s slightly scary how much I anticipate I have in common with the writer and performer Gioio De Cari. Also I think I may have taught a class in the classroom of this picture, maybe even with this haircut:

Second, I wanted to share a poem with you, written by Mary Oliver:
We will be known as a culture that feared death
and adored power, that tried to vanquish insecurity
for the few and cared little for the penury of the
many. We will be known as a culture that taught
and rewarded the amassing of things, that spoke
little if at all about the quality of life for
people (other people), for dogs, for rivers. All
the world, in our eyes, they will say, was a
commodity. And they will say that this structure
was held together politically, which it was, and
they will say also that our politics was no more
than an apparatus to accommodate the feelings of
the heart, and that the heart, in those days,
was small, and hard, and full of meanness.
Why I’m involved with #Occupy Wall Street
I get a lot of different responses when I tell people I’m heavily involved with the Alternative Banking group at #OWS. I find myself explaining, time after time, why it is I am doing this, even though I have a full-time job and three children (let’s just say that my once active knitting circle hasn’t met in a while).
I was not particularly activist before this. In fact I went to UC Berkeley for college and managed to never become politically involved, except for two anti-Gulf war protests in San Francisco which were practically required. While my best friend Becky was painting banners in protest of the U.S. involvement in El Salvador, I was studying tensor products and class field theory.
It’s true that I’ve been much more involved in food-based charities like Fair Foods since high school. One of the most attractive things about Fair Foods was that it acts as an outsider to the system, creating a network of gifts (of primarily food and lumber) which was on the one hand refreshingly generous, based on trust, and the other hand small enough to understand and affect personally.
I, like many people, figured that the political system was too big to affect. After all, it was enormous, did lots of very reasonable things and some unreasonable things; it didn’t solve every problem like hunger and crime, but the people running it were presumably doing their best with incomplete information. Even if those people didn’t know what they were doing, I didn’t know how to change the system. In short, I wasn’t an expert myself, so I deferred to the experts.
Same goes with the economic system. I assumed that the people in charge knew what they were doing when they set it up. I was so trusting, in fact, that I left my academic job and went to work at a hedge fund to “be in business”. I had essentially no moral judgement one way or the other about the financial system.
Once I got there, though, I had a front row seat to the unfolding crisis. As I wrote about, I got to see former Treasury Secretaries and Fed Chairman explain how shitty the securitized products are, that were currently being sold all around the world, and how they had no idea what to do about it except to tell everyone to get the hell out (which we can see has been harder for some than for others).
That meeting wasn’t the only clue I received that pointed to one thing: the experts had no idea what they are doing. The system was based on an overwhelming arrogance and network of vested interests. My conclusion as well as many other people’s.
On the other hand, it was a crisis. It was a fantastic opportunity to set up a better system. The optimist in me assumed that we would. I applied to work for the regulators to be part of the solution. When I didn’t get any offers I worked for a risk company instead.
After two years in risk, and no new system, I had to admit that there was no reason for optimism. The system is still being controlled by the same group of arrogant architects who argue that we can’t change it because then it would collapse. There’s always a problem with asking people on the inside to fix their problems. The politicians don’t understand enough about the financial system to know what to do, and the financial lobbyists telling them what to do are always protecting the banks.
Once I lost faith in fixing the problems, I felt pretty hopeless. I left finance, and considered working for a food-based charity in New York, but finally decided to stay a nerd since that’s what makes me happiest. I started this blog in a moment of hope that something as small as explaining how quants do modeling could be interesting to someone, that maybe the techniques used for so much destruction could also be used for construction.
Then something happened. It was the #OWS protest. I started going down to see if I could get people interested in talking about the financial system. Mostly people were only tepid, but sometimes people really wanted to know. I kept looking for a working group that would focus on this, and eventually I found one.
People talk about how the protesters are a bunch of lazy dirty hippies. There is certainly a group of people who don’t have access to baths, and there are people there who don’t work regularly (although that’s one reason they are there to protest). In fact there are some downright annoying people in the mix as well. But if you focus on those people, you are missing the point entirely. People also say they’re sympathetic, but that there’s no chance we could ever make a difference. I also politely disagree.
What this movement has done is to create a new opportunity for people to try to fix the system. I’m not saying I am 100% convinced it will work; in my practical-minded way, I think the best-case scenario is more like, we will influence the conversation.
But maybe influencing is enough, considering that very few people think things are working right now. At the policy level, we need to influence the conversation in the direction of showing what else could be done, rather than letting things stay the same for lack of a better plan. At the individual level we need to continue what has already begun: getting people interested and informed about the system and how it affects their everyday lives.
What’s the worst-case scenario? We have already seen it: it’s the past 4 years of doing nothing and letting the economy fall apart with no plan for improvement. The #OWS movement has already brought about a meaningful and hugely important conversation, and a sense of involvement by ordinary people, about what experts are doing with their lives.
This emerging conversation is perfectly illustrated in this Bloomberg article – not the article itself, which is strangely self-contradictory and even journalistically dishonest (it tells people to take their money out of Wall Street by investing with Vanguard in the stock market), but the comments on this article are some of the best comments I’ve ever seen on a business-oriented website. People are no longer letting themselves be spoon-fed bullshit.
The dirty hippies are a distraction, and the people who admit the system is broken but who obsess about them need to stop complaining about the embarrassing image and figure out how to help. People who think that we will never accomplish something without a few key experts should contact those experts and invite them to the meetings. Or tell me who they are and I’ll invite them. It’s time to try.
The Numbers are in: Round 1 to #OWS
This is a guest post by FogOfWar:
CUNA (a trade industry group for credit unions) just announced that at least 650,000 customers and USD $4.5 Billion have switched from banks to credit unions in the last five weeks. I think this is a pretty impressive showing for the lead up to “Bank Transfer Day”, and, as posted before, am a supporter of the CU transfers. A few quick points on the announcement:
Are those numbers driven by “Move Your Money” or BofA’s $5 Debit Fee?
A little of both, I suspect, and there’s no hard survey data (that I know of) splitting it out. The two points aren’t completely separate, as one of the points of “move your money” (at least in my mind) is to let people know that credit unions generally have lower fees than large commercial banks & it often makes financial sense to shift your account over regardless of your political views on “Too Big To Fail (TBTF)”.
So is 4.5 Billion a lot or a little?
It isn’t a big number in the scope of overall deposits, but it’s a really big number for transfers in just one month. For scale, the total deposits in all 11,000+ CUs nationwide are somewhere around $800Bn, and that’s roughly 10% of the total deposits in the US. So $4Bn (to make the math easy) is a 0.5% increase in deposits for CUs and somewhere around a 0.05% reduction in the deposit base of US banks in the aggregate. I suspect the transfers are concentrated in the large “final four” banks (BAC, JPM, C, WFC which, if memory serves, account for somewhere around 40% of deposits), so the reduction might be closer to 0.10% for the TBTF quartet.
Wait, those seem like really small percentages—why do you think this matters?
Well, because it’s a greater increase in deposits in one month than credit unions (in aggregate) got in the entirety of last year (and last year was a good year for CUs in which they saw their market share increase). People (rightly) don’t change their checking accounts lightly (there’s a lot of “stickiness” to having direct deposit/ATM cards/etc.—in short it’s a pain in the ass to change your financial institution), so this is a pretty impressive number of people and amount of deposits in this span of time.
Also (and this will play out over time), this could be the start of a trend. Certainly there seems to be a large uptick in discussion of “move your money”, and, as the idea percolates around there’s a lag between thought an action, so this well could be a slow build.
“A Slow Deliberative Walk Away from the TBTF Banks.”
Another important point is that, in fact, you really don’t want too many people moving their accounts in a short period of time for two reasons. First, a rush of people all removing their deposits at the same time is, in fact, a “run on the bank”. This is destructive for a host of reasons—in particular it can cause the institution on which there’s been a run to go into bankruptcy (regardless of whether that bank is otherwise solvent), and, let’s not forget, we the taxpayer are ultimately on the hook for the deposits of bankrupt commercial banks through the FDIC, which is funded by bank fees but backed by the full faith and credit of the taxpayer (and a BofA bankruptcy might put that backstop to the test). So, much as I disagree with many of the decisions of the mega banks, I don’t want the “move your money” campaign to be a catalyst for their insolvency proceedings.
Instead, what I’d really like to see is a slow steady whittling down of their deposit base, and thus their overall size, until they are no longer considered “to big to fail” and thus pose no danger to the taxpayers, as they will be free to make good or bad decisions and live or die, respectively, by them. In short, I’d like to see a “slow deliberative walk away from the TBTF banks” playing out over the course of the next 2-3 years.
The other reason is that credit union’s can only take deposits at a certain pace without running into issues with their own capital buffers and operations. This is a slightly technical issue, but with a substantive point behind it. In essence, absorbing a large growth in new deposits takes some time, not just from an operational perspective (ramping up staff, at a certain point opening new branches and ATMs), but also because more capital needs to be accumulated to provide a safety buffer for the additional deposits that have been taken on. From this perspective, the $4.5 Bn in 5 weeks is a “goldilocks” level—not to much to overheat, not too little to be a rounding error, but just right (OK, actually think it could be 2-3 times the pace without overheating, but everyone else loves to use that hackneyed “goldilocks” metaphor and I just felt peer pressure to frame it that way).
I read that it won’t have an impact on the banks—is that true?
In a word, “total fucking bullshit”. The deposit base is the skeleton of a bank—it’s what holds the whole thing together. Deposits are steady (essentially) free money. Money that can be deployed wherever the bank finds interesting at the moment: loans to customers, speculative exotic derivatives, new branches, foreign investment, whatever. Moreover, if retail deposits mean so little to banks, then why in the world do they spend so much advertising coin chasing them? Generally for profit institutions advertise for products that are profitable to them, not one’s that are irrelevant. QED.
That’s true over the long term. It is worth noting, however, that at this exact moment in time the banks are flush with cash sitting idle on deposit with the fed. http://www.cnbc.com/id/44019510/Bank_of_New_York_Puts_Charge_on_Cash_Deposits Which, by the way, makes it perfect timing for the “move your money” campaign. As I said before, I really don’t want a “run” on the banks, and the fact that banks are flush with cash currently means they’re relatively safe in the immediate moment from a loss of deposits.
But the real reason you’re still seeing Chase commercials on TV even though they’re flush with cash doing nothing at the Fed, is that Chase knows that most people rarely change their primary checking accounts. The accounts that are moving over now are (statistically) gone for good. Later, when that flush cash at the Fed is no more and the banks want the easy money of a wide retail deposit base, they’ll find it very difficult to bring those people back. Not because credit unions are really awesome, just because people really don’t like switching accounts—BofA has to spend a lot of energy to bring in a new account from another institution and doesn’t actually care if it brings it in from lower east side people’s or from Citibank (money is fungible).
Lastly, and perhaps most important, the primary checking account is the primary point of entry to our financial lives. Big banks like the free money you give them on deposits, but equally much they like the chance to have your credit card business, your mortgage and car loan business, your insurance business, your investing business and possibly your retirement and college savings business. All that ancillary business can be (and very much is) statistically quantified on a per-account average basis. All those cross-sells add up over time to big numbers.
FoW


